Tuesday, 16 January 2018

My Money-Saving Tips Towards Becoming a (Millionaire)

Okay. These tips might not help much towards becoming a millionaire.

However living in Singapore is not easy when things are not exactly cheap.

Hence in order to live more comfortably we have to build up our savings for the proverbial rainy days (not the kind that we experienced these few days) and at the same time achieve income increment that at least beat the inflation rate.

There are essentially two ways to go about achieving the former.

One: Increase our income.
Two: Decrease our spending.

Easy isn't it?

Since increasing our income isn't always within our control especially when it comes to salary, the other way is to look out for money-saving opportunities in our daily lives.

As a matter of fact, I did not consciously set out to do these acts. Somehow they have became part and parcel of my life after so many years, so much so that it is almost natural.

So here is goes.. Some of my money-saving tips for sharing..

1) Not ordering canned drinks at coffee shops

Canned drinks are by far the most price-inflated drink in a typical coffee shop. For the same canned drink that costs $1.50 at the coffee shop, I can get it at the neighbouring super market at half the price or less. Luckily I'm not a particular fan of canned drinks too.

2) Return appetisers and wet tissues in restaurants

Usually restaurants place appetisers like peanuts and pickles to your table before you even begin ordering your meal. However since I don't really fancy appetisers like these, I usually ask the staff to bring it back.

Same for the wet tissue. I don't really mind using my handkerchief or own tissue to wipe my mouth after meal.

3) Always check the bill

This is important. Always check your bill before and after payment. I have on more than one occasions been billed wrongly at eateries and super markets.

Simply by checking, I have saved quite a sizeable amount over the years.

This also applies to all your purchases, not only for meals and groceries.

4) Buy Online

I'm not saying everything must be bought online. Personally for items such as shoes, I still prefer to buy in brick and mortar shops.

However certain things like hand phone covers, casual attires and household items do indeed cost much lesser than in physical shops.

One of my recent online purchase:


Cost me a grand total of S$47.90 and 1 hour for assembly. Worth it isn't it?

5) Compare and Compare

This has been my habit for the longest time whether in my private life or in my work.

Shops like Watsons and Guardian are often located near each other in the mall. It helps to compare the price of same product between similar shops before buying. Sometimes the price difference can be significant.

6) Bulk pack isn't always cheaper

Again, this require some work on your part. Whip out your hand phone and calculate the unit price of the bulk pack item that you are eyeing.

There are times where we found the single pack is in fact cheaper than the unit price of the bulk pack of the same item.

7) Discount cards

Member cards like the Kopitiam card need no introduction. 10% discount off meals by using the card is a no brainer.

I don't usually pay to sign up for member card. But sometimes I do that if the advantages outweigh the price. For example I am a Jumbo member as I figure the savings achieved easily exceed the member fee.

8) Use credit card as far as possible

My style is to use my credit card as far as possible especially for big ticket items.

Nowadays cards like OCBC 365 card and UOB One card are tied to the respective savings account. By using the card, I can get cash rebate on my card and increased interest on my savings. Win-win.

Importantly: Pay off all the bills before due date.

9) Movie tickets

Yes I do watch movies too though I may sound miserly from above.

The trick here is to buy the tickets on the spot instead of online. Simple enough but I have friends who like to buy online thus incurring unnecessary surcharges.

However I heard from a friend that the surcharge is a fixed amount no matter how many tickets are bought. If that's true then bulk purchase of tickets might be worth it after all.

Having said that, I have an even better deal when it comes to movie tickets. As a M1 customer, I get to watch movies for free on Sundays! M1 customers enjoy one-for-one tickets on Sundays at Shaw cinemas. It used to be Cathay cinemas though.

Caveat is that I need to wake up early to buy the tickets as there is a limited number to this deal.

Nevertheless to me, it pays to wake up early and at the same time I get to spend more quality time with my loved ones.

10) Free parking

I always look out for free parking when I drive. It costs a lot to drive in Singapore so every little saving helps.

Certain malls offer free 2 hour lunch time parking.

Some areas offer free parking after 5 pm.

On Sundays there are plenty of free parking in estates around our sunny island. Even those close to malls. Very often I see cars queuing up to enter the malls' car park. But just a stone throw away there is free parking available at a HDB block and I don't even have to wait to enter.

Some times the free car park is 10 min walk away. But that is not an issue for me and my family. The walk back to the car park can be a nice time for a heart to heart talk.

Monday, 1 January 2018

Goodbye 2017 Hello 2018


Happy New Year everyone. Hope you had a good 2017 and may you stay healthy and happy in the new year ahead.

Actually I have written this post halfway through to take stock on the different aspects of my life in 2017 and to start 2018 with some goals. 

However I was simply too busy to finish it before end 2017. Nevertheless it's meaningful to post this on the first day of the new year I guess.

Here it goes..

Work

On the work front, there is major change in 2017. I have left my previous company in which I am also a minor shareholder, to strike it out on my own.

Business has been not bad so far. Customers have been supportive and I am thankful for that.

My focus remains on growing the business and working on adding a new capability to the company by this year.

Other Incomes

Previously I set a target of doubling my side and passive incomes of S$2,712.86 by 2017.

Result for 2017: S$6,527.40 (Target met)

Moving forward I have to set a more modest target for this year due to a number of reasons. There is no point setting an exorbitant target and failing to achieve by year end. Also it's not my style to set an easy target to bluff myself when I achieved it later.

Hence the target for this year will be 20% growth in this category.

Equities and REITs

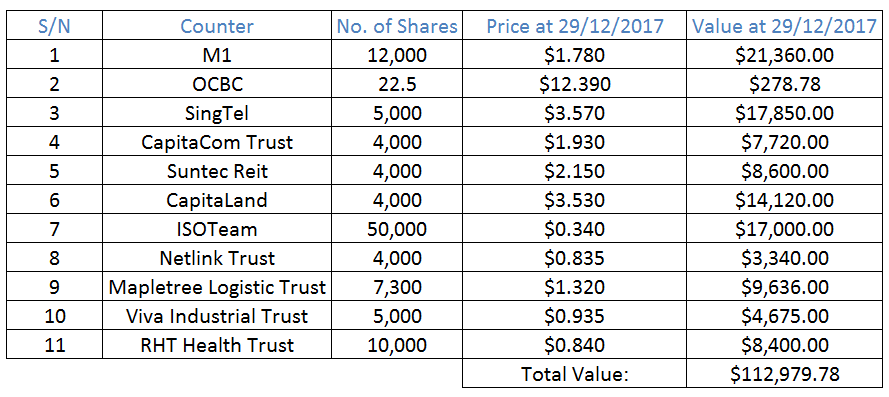
My holdings as of 29/12/2017:


Most of the counters in my current portfolio belongs to my long-term income holdings with the exception of CapitaLand, ISOTeam and RHT Health Trust.

CapitaLand is meant to be a trading stock. However it might turn into part of my long-term holdings if the dividend continues to grow which is the case for the past four years. Based on my purchased price, the yield is 3.36%. Below my target of min. 4% but still not bad actually.

Currently sitting on 17.9% paper profit.

ISOTeam is a loss-making counter for me so far. However I will continue to hold as I believe in it's growth potential and strength of the management team.

Unless something fundamental changed drastically, I intend to hold it till at least the next AGM. I'm pretty confident this year's results will be glowing for ISOTeam.

The share price has hit $0.42 some time last year. I don't see why it cannot happen again in the near future.

And the bit of dividend helps to cushion the paper loss so far.

RHT Health Trust is a pure punt on the Fortis buyout. Results of the deal (or no deal) should be finalised by this month if I remember correctly.

If the deal pans out this should leads to a small capital gain for me. If not I'll have to see what's the future plans from the management and of course the future dividend trend for the trust.

In summary,

1) Yield on Total Amount Invested 2017: 1.48% (Drag down by couple of trading losses)

2) Yield of Income Portfolio 2017: 3.62% (No dividend from Netlink Trust and Viva Industrial Trust yet)

3) Cumulative Yield of Income Portfolio: 5.42% (No dividend from Netlink Trust and Viva Industrial Trust yet)

2017 was also the year where wifey started her passive income portfolio. Her holdings as of 29/12/2017:


Personal

Last but not least, I also wish to share a piece of good news. I'm going to be a dad soon. Yeah!
 
My wife and I are expecting our first child this year and coincidentally he or she shares the same zodiac sign as me! 😄

Sunday, 24 December 2017

Recent Actions - Nov and Dec 2017

Short update for the months of November and December to conclude the year.

1) Bought 5,000 shares of Viva Industrial Trust @ $0.955 for my income portfolio. Did the same for wifey's as well.

2) Bought 3,000 shares of SingTel @ $3.64 for wifey as part of her income portfolio after recent XD.

3) Bought 10,000 shares of RHT Health Trust as a punt on the acquisition by Fortis.

4) Received dividend of S$325 from ISOTeam.

5) Received dividend of S$99.32 from Suntec Reit.

6) Sold 3,000 shares of Wilmar after signs of price weakness and failure to break through resistance. Could have earned more but decided to lock in profits first.

Monday, 4 December 2017

Review of Dim Sum Haus

In food paradise Singapore, dim sum has always been one of the frequent choice of food for my wife and I. So we decided to make a trip to one of the newer establishments in town yesterday:

Dim Sum Haus @ 57 Jalan Besar

It was our first time to this shop and having heard good reviews about this place, we went with high hopes.

First off, there are free parking around the area on Sundays. Otherwise Jalan Besar MRT station is less than 5 min walk away.

There are no outdoor seating as far as I can see. All the seats are indoor with air conditioner.

We reached there around lunch time and there were still couple of tables available.

Looking through the menu which although not very extensive, has enough choices to satisfy most people, we decided to order the following (with my personal score based on taste in bracket beside):

1) Plain congee (7/10)

Seasoning and texture of the congee are done just about right. Along with the accompanying crispy you tiao, this dish is not bad.

2) Pan fried carrot cake (6.5/10)

Surface of the carrot cake is not crispy enough. However the carrot cake has the right balance between hardness and softness. You can taste the lup cheong when you bite into it.

3) Crispy chee cheong fun with shrimp (7.5/10)

This is the best dish among what we ordered. First bite into the chee cheong fun you can taste the nice balance of the soft chee cheong fun and the crispiness within. The seasoning is pretty normal, about the same as other places.

4) Fried mee sua kueh (6.6/10)

Not impressed by this. First impression was the kueh has been over fried based on the dark brown colour of the kueh surface. Taste-wise is a tad too salty. Prefer the Swee Choon version.

5) Har gau (6.8/10)

The prawn is fresh and the thickness of the har gau skin is just right too.

6) Salted egg custard bun (7.2/10)

This is a refreshing change from the usual liu sha bao. The crispy exterior of this version adds another dimension to this common dim sum. The salted egg custard is nice too. However from the second piece onwards it gets a bit too much.

7) Hong Kong style egg tart (6/10)

This was quite disappointing. The crust is biscuit-like. The egg is a tad too solid. Personally prefer egg tarts with flaky crust and the egg 'bounceable' when you shake it.

Service:

Considering the place was not even full house, the service was quite slow. Took about 20 min for the first dish to arrive after we placed the order.

Catching the staff's attention was a bit of a challenge.

The staff's finger came into contact with our food when she was clearing some empty plates on our table. I'm sure it's not on purpose though.

Price:

About the same as elsewhere. Most dishes are within $5.00.

NETS payment, minimum $10.
Credit card payment, minimum $50.

Summary:

Overall nothing major to complain about. Neither is there anything impressive about this place.

This seems like just another place that serves dim sum. I can't see any differentiating factor between this place and others.

Would I go back again? Probably not on my own accord.

I would stick to my other tried and tested dim sum places where I frequent.

Disclaimer: This is my personal view. I'm not related to any of the establishments nor its owners in any way as far as I know.

Wednesday, 15 November 2017

A Vote of Confidence for Wilmar

Two days ago Kerry Group Limited acquired $225,417 worth of shares in Wilmar at an average price of $3.45.

This has increased their stake in Wilmar to slightly over 11%.

Of particular significance is the price of $3.45 which might be the fair value deemed by the big boys.

This is no doubt a good news and a vote of confidence for Wilmar.

Personally I will continue holding my small stakes. It makes sense for small players to follow the big boys trend isn't it?

Snippet 1: Our former foreign minister Mr George Yeo is the chairman of Kerry Logistics and director of Kerry Holdings Ltd.

Snippet 2: Malaysia's richest man and sugar king Mr Robert Kuok is the chairman of Kerry Group Ltd.

And a big source of his wealth is his stake in Wilmar.

Tuesday, 14 November 2017

City Developments vs CapitaLand

The recent release of CapitaLand's latest financial results sent the share price downwards despite it being a decent set of results.

As I was thinking about this, it led me to the next questions.

Why is it that City Developments can be trading in the region of S$12+ while CapitaLand continues to languish at S$3+ and what are the differences between the two companies?

It piqued my interest as I have never delved into City Developments before and I set to find out more.

The comparisons gave me a big surprise.


 Overview of City Developments (CDL)

City Developments Limited has a history of more than 50 years since their beginning in a small rented office in Amber Mansions on 7th September 1963.

They have since evolved into a Singapore-listed international real estate operating company with presence in 26 countries including Singapore, Australia, China, Japan, UK and rest of Europe.

CDL's portfolio consists of residences, offices, hotels, serviced apartments, integrated developments and shopping malls.

One of their most recognised brands is the Millennium & Copthorne hotels chain.

CDL's core markets are UK, US, China, Japan and China.


Overview of CapitaLand (CPL)

CapitaLand group is a property company created from the merger of Pidemco Land and DBS Land in November 2000.

Since then CPL has grown to become one of Asia's largest real estate companies. Based and listed in Singapore, it is an owner and manager of a S$85 billion portfolio comprising integrated developments, shopping malls, serviced residences, offices, homes, REITs and funds in over 30 countries.

It is also one of the largest investment management businesses in Asia with 14 real estate private equity funds and 5 REITs worth over S$47 billion in assets under management.

CapitaLand acquired Raffles Holdings and The Ascott Group in 2006 and 2008 respectively and the latter is the world's largest international serviced residence owner-operator.

Singapore and China remain the two core markets of CPL, totalling 82% of the group's total assets.

Comparison of the Financial Figures


As mentioned earlier I have never studied CDL before. But inferring from the share price I expect the scale of their business to be much bigger than CapitaLand.

However this is exactly the opposite.

No matter which metric you look at - cash holding, revenue, PATMI, assets or AUM, CapitaLand is clearly the bigger player.

Exception is the EPS where CDL is slightly higher than CPL.

Note: Figures are from the 3Q17 financial reports of both companies.

Valuation

I then did some quick calculations for the latest P/E and P/B ratios as a gauge of their valuation.

Again CPL is the winner here. In fact CPL is currently trading under book value whereas CDL is trading slightly above book.

Future Growth of City Developments

In 2016 CDL acquired 20% stake in mamahome - China's fast-growing online apartment rental platform.

In 2017 CDL acquired 24% stake in Distrii - China's leading operator of co-working space.

These synergistic acquisitions are a move away from their traditional sources of income and it's nice to see this forward-looking direction of the management.

In the near term, CDL has several upcoming local residential projects including New Futura, a Tampines Ave 10 project and South Beach Residences.

Upcoming overseas residential projects include 1 in China, 7 in UK and 1 in Japan.

CDL also embarked on 2 projects in Australia for luxury retirement village development with expected completion in 2020 and 2021.

CDL is also actively engaging in asset enhancement initiatives for various Millennium & Copthorne hotels in New Zealand, UK, KL and Singapore.

Future Growth of CapitaLand

CapitaLand has over 8,000 residential units with a value of RMB 13.8 billion sold in China and expected to be handed over from 4Q17 onwards. 10% of the value is expected to be recognised in 4Q17 and 70% in 2018.

On the shopping mall front, CPL opened their largest mall - Suzhou Centre Mall three days ago on 11th Nov 2017.

CPL is also set to continue their expansion in markets such as Vietnam and Indonesia. Their residential project in Vietnam - d'Edge is close to 100% sold.

SingPost Centre opened on 12th Oct 2017, is CPL's first managed mall in Singapore under management contract.

Apart from the above, CPL has 6 management contracts in China to date as well.

CPL also launched CapitaLand online mall on Lazada on 16th Oct 2017.

It's good to see these new initiatives from CPL which show that the management is actively looking for new income sources.

On the serviced residences front, Ascott is on track to achieve their target of 80,000 units under management by 2020.

Summary and Conclusion

Beside the fact that both are real estate companies, City Developments and CapitaLand are also similar in terms of assets composition, development type and geographical composition.

In terms of business scale, CapitaLand is much bigger with significantly higher top and bottom lines compared to City Developments.

However in terms of share price, City Developments is the clear winner. Since January this year, share price of CDL has rose 50% while share price of CPL has increased by 18%.

Shareholders make money either through dividends and / or capital appreciation.

Since both CDL and CPL are not fantastic dividend counters I will look at capital appreciation instead.

For capital to appreciate, the share price must appreciate. Simple.

Based on the basic valuation metrics, CapitaLand share price has much room for appreciation.

However since the share price has dropped after the release of 3Q17 results, is it because shareholders feel that the results are not comparable to the previous year?

Comparing Y-o-Y revenue, latest 3Q indeed fell by 0.1%.

However Y-o-Y, profit increased by ~70%, EPS increased from $0.179 to $0.302 and ROE increased to 4.97% from a negative figure.

This is what perplexes me. The company is earning more and generating more returns on the shareholders' investment but the market feels otherwise.

Can anyone enlighten me please?

Friday, 3 November 2017

Viva Industrial Trust - My First Foray Into Industrial REITs

Today (actually it's yesterday since it has passed midnight) marks my first foray into the industrial class of REITs if I don't consider Mapletree Logistics Trust as industrial.


Viva Industrial Trust is not a pure industrial REIT. It has a hotel among its properties.

I have been monitoring Viva Industrial Trust for some time. When the price dropped more than the dividend post-XD today, I decided to take advantage of this and buy into this counter @ $0.955.

Ideally I would like to go in below $0.95 but guess I am not that disciplined.

Results from Viva's latest quarter look promising.


Comparing Y-o-Y and Q-o-Q,


Other results,

Gearing is reasonable at <40%.

WALE is 2.8 years. To be honest I would prefer this to be higher.

And portfolio occupancy is 90.9%.

As a matter of fact, the above figures allude to the good fundamentals and good management of the trust.

Furthermore with the opening of the Downtown line station connecting directly to UE BizHub East, there is a real possibility of upcoming positive rental reversion and increment of the property value.

However the deal clincher for me is the AEI done for their Viva Business Park (VBP) in Chai Chee. I've been to VBP several times in the past for business meetings before they commenced the AEI.

Post-AEI, I've went back several times with my wife and what a world of difference the initiatives made!

The most obvious improvement is the number of retailers and anchor tenants such as Harvey Norman and Decathlon taking up space in the business park.

This is a far cry from the old VBP where majority of the tenants are commercial entities and the only retail shops on the ground floor are cafes and such.

The effort made for the AEI is actually visually-obvious. It changes the whole vibe of the business park. And I have to say I am impressed by what I see.

Paying at $0.955 a piece for Viva means paying a premium to its NAV and this is usually what I don't do.

However I see limited downside and much upside to the price due to the increased buying interest in this REIT, value-realisation of UE BizHub East and potential of increased income from VBP.

The way I see it, Viva will break $1.00 soon.

My plan when I placed the queue order today was this:

a) If the price appreciated within these few days, I might do a short term trade.

b) If the price drops, I will hold as part of my income portfolio. A dividend yield of nearly 8% doesn't hurt.

Cheers.