Showing posts with label UOB One. Show all posts

Thursday, 27 August 2020

Addition to My Safe Stream of Passive Income

All along, my POSB savings account has been a low interest bearing account. Just maintaining it for the sake of nostalgia and some Giro arrangements like monthly insurance and charity contributions.
 
However recently I discovered the POSB Cashback Bonus which turned out to be a great addition to my passive income from interest / cash back from my bank accounts.
 
I know I have been slow to this but it's better late than never.
 
And I don't even need to sign up for a separate account for this. All I need to do is to log in to my iBanking and enroll my existing POSB account into this Cashback Bonus scheme.
 
Less than 5 min job.
 
Why do I say this is a great addition to my passive income from bank accounts?
 
That's because:
 

Yes, a whooping 3% cashback on my monthly home loan instalment with the bank.
 
This rate by itself already beats most, if not all the other cashback / high interest savings accounts out there.
 
Do note that you have to meet at least 3 of the criteria in order to qualify for the cashback.
 
Obviously the caveat here is that this scheme will benefit more for those who has home loan, insurance and / or investments with the bank.
 
Also, if you are maintaining a high average balance in your POSB or DBS account, the DBS Multiplier might be a better choice for you.
 
The difference between the POSB Cashback and DBS Multiplier account is that the former doesn't care how much is in your savings account as the cashback depends solely on you meeting the minimum 3 criteria while the latter gives interest based on the amount in your account balance.
 
I've done a quick calculation. With this addition of cashback, I am looking at a monthly inflow of $70+ conservatively speaking, just by doing what I have been doing all this while without the need to change my lifestyle.
 
$70+ per month or $800+ yearly. While this might not be a lot of money to some, it's good enough for a short trip to Bangkok (almost a yearly trip for us previously) or cover some milk powder expense. Haha..
 
In short,
 
The POSB Cashback Bonus scheme will benefit those who has a home loan, insurance and / or investments with the bank yet at the same time does not maintain a high account balance. 
 
So this is the latest tweak to my safe stream of monthly passive income, at least until the banks change their interest / cashback criteria again.
 
By the way this is not a sponsored post. Just a sharing of another great way to earn more passive income for people who can benefit from it.

Thursday, 2 March 2017

OCBC 360 vs UOB One - Latest Comparison


So you guys probably already know that OCBC has changed the terms and conditions of its 360 savings account again.

If memory serves me well, this is the 2nd time they have changed those conditions.

Initially it was 1% interest P.A. for each of its original 3 categories. After that it was changed to 0.5% for couple of the categories. Now it's down to 0.3%.

While it is not totally unexpected, it is still disappointing nonetheless.

With the new conditions (interest rates) in place from 1st April 2017 onwards, it would serves us well if we can do an apple to apple comparison with the next closest saving account to see which benefits us most.

With that in mind I did a comparison between the OCBC 360 account and UOB One account.

First off, the difference between the existing OCBC 360 conditions and the new conditions from April onwards.


As you can see, interest rate has dropped in two of the categories while new condition has been set.

Personally I am able to get 2.25% + 1% on incremental saving amount on current conditions. Once the new scheme kicks in, realistically I should be able to get 1.85%.

Now, the interest rates offered by UOB One account.


Interest offered by One account is slightly different in the sense that the rates are on step up basis.

So which is the better account in terms of interest rate for the man in the street?

For this question we do a case study based on two scenarios as follows.

Case Study 1:

For the average Joe who maintains $20,000 in his account every month and is able to get 1.85% from his OCBC 360 account from April 17 onwards or 2.05% from his UOB One account.

On top of that he also spends at least $600 on his credit card every month. Since the cash rebate for OCBC 365 card is mostly between 3 - 6%, we use a mid figure of 4% for our average Joe.


Case Study 2:

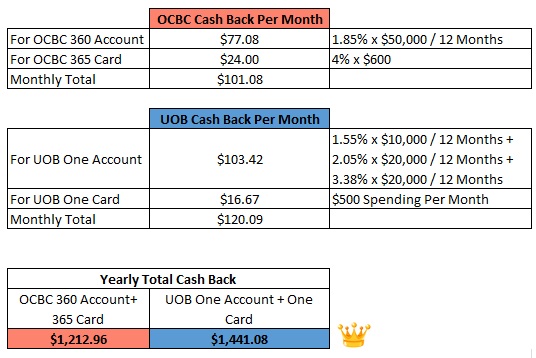
For the richer average Joe who maintains $50,000 in his account every month and is able to get 1.85% from his OCBC 360 account from April 17 onwards or 3.38% from his UOB One account.

On top of that he also spends at least $600 on his credit card every month. Since the cash rebate for OCBC 365 card is mostly between 3 - 6%, we use a mid figure of 4% for our average Joe.


Case Study 3:

For the even richer average Joe who maintains $70,000 in his account every month and is able to get 1.85% from his OCBC 360 account from April 17 onwards or 3.38% from his UOB One account.

On top of that he also spends at least $600 on his credit card every month. Since the cash rebate for OCBC 365 card is mostly between 3 - 6%, we use a mid figure of 4% for our average Joe.


In conclusion, you can see that with a larger savings amount up to $50,000, the UOB One account offers a better deal than OCBC 360 account.

However if your savings amount starts to exceeds $50,000 you might want to take a closer look at the OCBC 360 account since the interest rates are valid up to $70,000 whereas UOB One account only offers 0.05% base interest for savings above $50,000.

(Thanks to reader Vince Chew who pointed this out)

If you are like the average Joe in our case study who maintains a lower amount in his savings, OCBC 360 is probably better for you.

For myself, I will still stick with my OCBC 360 account FOR NOW as most of my funds are currently in investments.

It's not worth the hassle for me to switch my Giro billings.

Furthermore UOB, like other banks, can change the conditions for their UOB One account anytime. So I will adopt a wait and see attitude first.