April 2019
Portfolio Value after market close: S$90,017.44
Wifey's Portfolio Value after market close: S$45,681.02
Purchases: None
Sold: 5,000 shares of CapitaLand
Comment:
CapitaLand
Balanced 4,000 shares of CapitaLand at $2.98. Will continue to keep for its ~4% dividend while waiting for its breakthrough.
Cash has been growing with my recent sale of M1 and CapitaLand. Intend to put it back into the market but most of the reits and income stocks in my watch list are overpriced at the moment.
Not going to buy for the sake of buying. Will continue to monitor the market for entry opportunities. Meanwhile the cash will stay in my OCBC 360 account for the 2% interest.
RHT Health Trust
RHT Health Trust is making some interesting movements in the past couple of months with the name change and appointment of a new chairman and directors, some of whom came with healthcare management background.
I don't think these are done for fun. I'm looking forward to the possible good news ahead. Hopefully the new CEO will inject some attractive new assets for the shareholders.
Will continue to hold onto my shares.
Japfa
Japfa still seems to be affected by the swine flu news though fundamentally nothing has changed. Will be monitoring the share price with a view to add more.
Showing posts with label M1. Show all posts
Showing posts with label M1. Show all posts
Tuesday, 30 April 2019

Saturday, 30 March 2019
Mar 2019 Portfolio Update
March 2019
Portfolio Value after market close: S$106,881.07
Wifey's Portfolio Value after market close: S$44,333.53
Comment:
1) Realised a 4.94% gain on M1 after accepting Konnectivity's offer. Not bad for a 3 years holding considering the prior circumstances.
2) Contemplating whether to take profit on my reits especially for CCT which is at 40+% gain now.
Thursday, 21 March 2019
Stock Screening Results - Mar 2019
With the recent cash from the sale of my M1 shares, I have to look for other dividend-paying stocks as replacement(s) to at least maintain and hopefully increase my portfolio yield.
So I turned to my best friend for help. Stock screeners.
Usually I used the StockFacts screener from SGX. However for this time I also tried Yahoo Finance screener for curiosity sake.
The criteria I set for the screen are as follows:
P/E Ratio: < 20
One of the most fundamental of valuation screeners. It is more meaningful if the PER is compared among companies in the same industry.
However in this case I usually set it to 20 as a rudimentary guard against overpaying.
Net Profit Margin: At least 10%
10% is the minimum margin in my opinion, for a company's sustainability.
Debt to Equity Ratio: < 50%
Obviously gearing is one of the most important metrics in terms of risk management. 50% is the most I can accept unless there are very good reasons for the high gearing.
Price to Book Value: < 1
I do not like to overpay for a stock. However having said that I have done it on a number of occasions usually due to a combination of other factors which paint an overall rosy picture of the stock.
Dividend Yield: At least 5%
Ideally 5% is the minimum for my dividend stocks which is not too high honestly.

As you can see, the criteria I used are geared towards screening of income stocks suitable for my income portfolio. Not so much on growth or other value stocks.
Interestingly the result from Yahoo Finance screener is almost identical to that of SGX StockFacts screener except that the former includes one more counter in the screening result - Metro Holdings Ltd.
Here are the results.


Another interesting observation is that my previous screenings say 1 - 2 years back, almost always yield a 2 page long results.
However this time only 9 counters appear from the StockFacts screening.
Is the market worse or better than before? Or are most stocks overpriced now?
I think apart from the surface results from the screening, we can also delve deeper and we will be able to get a feel on the current market conditions.
Back to the screening results, I will do more due diligence into 1) Frasers Commercial Trust and 2) Sasseur REIT.
Friday, 15 March 2019
Goodbye to M1
I knew my relationship as an investor with M1 has came to an end when I saw a huge jump in my bank account yesterday.
True enough, it is the sum from my acceptance of Konnectivity's offer.
In all I made a small net profit of 4.9%. Good enough for me considering I was staring at huge paper loss at some point in time.
On the bright side I'm still walking on the sunshine with M1 for my mobile and broadband.
All the best to M1 for their new ventures which I had and still have high hopes for.
Next step for me is to redeploy the sum of money to another yield-accretive counter.
Friday, 8 March 2019
SGX Securities Borrowing and Lending Programme
It seems like a long time since I signed up for SGX securities borrowing and lending programme (SBL).
In fact I have forgotten about this until today when I realised $4.94 was credited to my bank account.
Upon checking my CDP statement, I found out that 11,000 of my M1 shares were borrowed (on loan) for 2 days last month.
In the probably 2 years since I signed up, this is the first time my shares got borrowed.. Haha
And of all shares, M1? This is some logic that I don't understand. Perhaps this is why I remained as an average retail investor.
As I can't find any formula online on the expected returns for borrowed securities, I decided to do a back-of-the-envelope calculation myself.
Calculations
No. of Shares On Loan: 11,000
Closing Price of Share While On Loan: $2.05 & $2.06
No. of Days On Loan: 2
Returns: 4% (this information is available online)
11,000 shares x $2.05 × 4% / 365 days x 2 days = $4.94
Please feel free to correct me if this formula is incorrect.
It's nice to have some additional lunch money sometimes.
Till next time.
Tuesday, 1 January 2019
Taking Stock of 2018

Leaving 2018 and entering 2019, time for a quick roundup of my 2018 and my little wishes for the new year ahead.
Work
This year is my company's 2nd year of operation.
Results so far are a tremendous improvement over last year in terms of revenue, profits and scale of projects secured.
Although revenue is still about $75,000 shy of the target I set for myself, I have two more months to 'chiong' before end of my financial year. Hopefully I can close the FY even more beautifully.
In terms of business offerings, I have added the Design, Installation and Maintenance of Solar Photovoltaic (PV) system to my products and services recently.
This is actually synergistic to the other portion of my business which is environmental engineering, particularly in pollution control systems.
As I mentioned before, one of my investment guidelines is to ride along with the macro trend.
I believe Solar PV system is the way to move forward especially in a country like Singapore. Hence I made a deliberate effort to take up a course in this field and graduated from it recently.
This also means I have achieved my aim of adding a new capability to the company by this year.
Moving forward, my focus continues to be growing the business and if possible purchase an office space as part of my recurring income plan.
Other Incomes
Previously I have set a target of achieving S$7,832.88 for my side and passive incomes in 2018.
Actual passive income achieved for 2018: S$6,069.08
Actual side income achieved for 2018: S$3,042.86
Result achieved for 2018: S$9,111.94 (Target met)
For 2019 I am going to target another 20% growth in my dividend income as I will probably be drawing down a portion of my portfolio for some expenses.
For the side income in 2019, there is actually a much higher room for growth. I am in the midst of discussing a venture which if materialised, will contribute a significant amount to this category.
However I do not want to count my chickens before they hatch. Hence targets for 2019...
Targeted passive income for 2019: S$7,200
Targeted side income for 2019: S$3,000
Equities and REITs
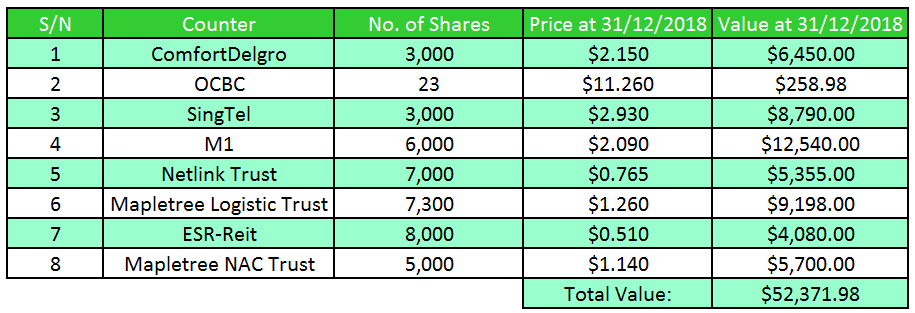
My holdings as of 31/12/2018:

With the exception of M1, all the counters in my portfolio closed at a lower price this year end compared to last's.
In 2018, I've added another 5,000 shares of CapitaLand, added another 4,000 shares of Netlink Trust and bought 4,000 shares of Mapletree NAC Trust. Total capital injection is $25,820.
Excluding the capital injection, my portfolio value returned -13.7% compared to last year. A loss of more than $15k.
What a humbling experience. It shows how much of a fool I am in the stock market.
In summary,
2) Cumulative Yield of Portfolio: 8.10%
Similarly, wifey's portfolio also dropped in value ($41,431.98) compared to last year ($41,919.78) if capital injection is excluded.
Personal
Baby M who arrived on Father's day 2018, never fails to bring a smile to our face. She is making lots of funny sounds and lots of movement nowadays.
Really a different kind of joy.
Our biggest wish is for her to grow up happily and healthily.
I always believe we should not forget to help others if we can.
Though my investment portfolio performed less than admirably, I donated $550 to a selection of charities in 2018. This is on top of my monthly Giro donations to Community Chest and NKF.
Thanks to giving.sg, it is so convenient nowadays to make donations and volunteering.
Last but not least, I wish everyone a happy new year ahead. Good health and good wealth!
Thursday, 8 November 2018
Why I Feel M1 is a Hidden Dragon
Recently there are a number of happenings surrounding M1.
Firstly is the offer from Konnectivity which everybody would have heard of by now.
And earlier this week it was announced that CEO Karen Kooi will be stepping down on 6th Dec.
It is my belief that the first point stated above is related to what I am going to write as follows.
TL:DR version.
M1's involvement in smart metering will be the next driver for its business.
Previously I have written about how I feel about the potential of M1's new acquisitions and initiatives including the move towards IoT.
Amongst IoT, I personally believe that smart metering will play a major role in the transformation of our country.
With M1's involvement in the smart metering environment, probably Keppel and SPH know how 'big' is the potential (and value) and how much it will benefit M1 in the coming future.
Hence the offer for buyout.
As it stands currently the biggest issues that Singapore face is water and power.
With the trend towards NEWater and desalination both of which requires tremendous amount of power, the water issue is essentially a power issue as well.
Furthermore with the recent power outage which affected more than 140,000 consumers in many parts of Singapore on the night of 18 Sept 18, it is apparent that certain elements of our power generation is not equipped to cope with sudden peak demands.
This is one of the areas where smart metering can comes into play.
What does a smart meter do?
1) A smart meter measures and records energy usage in short intervals.
2) It provides two way communication at the meter. Energy usage is communicated in real time allowing the utilities to be remotely monitored.
3) It can facilitate better electricity supply, better in-home data and better load programs.
4) Remote load control. A smart meter can be programmed so that high usage equipment can be turned on and off based on time or price or other parameters through the communications.
5) Exported power generation can be measured. This is useful with the trend towards solar energy generation in Singapore.
6) Outage detection. Utilities service providers can remotely check the status of any meter.
7) Meter tamper detection. A smart meter can also be monitored to see if it has been accessed without authority.
8) Remote time synchronisation. A smart meter's internal clock can be kept accurate without site visits.
9) Any events e.g. voltage spikes, voltage drops, outages, etc can be recorded by the meter.
Referring to points 1 - 4 above. Imagine if Singapore is already a smart grid nation, the outage on 18 Sept would likely have been prevented or at least rectified more quickly.
Furthermore imagine the man-hours saved! The SP services guys will not need to check the meters outside your house every other month.
How does it helps to improve our national electricity market?
As Singapore moves from centralised power generation towards integration with distributed generation, smart grids with smart metering may be the solution to many problems currently faced.
Firstly the reliability of the grid is always a great concern. Smart grids make troubleshooting grids much easier as information flows digitally from all areas of the grid making it easy to determine the problem source.
Secondly our electricity demand has been increasing and generators may struggle to supply the power required during periods of peak demand. Smart grids with demand side management (DSM) can ease the pressure on the supply by giving consumers incentives to lower their energy consumption and use electricity more efficiently during peak periods.
Thirdly the increased use of distributed generation (particularly from renewable energy sources) poses new problems for utilities companies who must integrate this new source into the grid. Smart grids have the capacity to integrate multiple power flows hence allowing for better integration of these technologies through improved communication.
M1's move into the smart metering segment means that it is directly involved in the transformation of our national electricity market which may well proved to be the game changer or at least a new major driver for M1 business.
Saturday, 29 September 2018
M1
It was nice seeing the share price of M1 opening at above $2 the day after trading halt is lifted. It has been a long time since M1 crossed over that mark.
By now everybody would have known this is due to the offer from Keppel and SPH. Some have already sold their shares amidst the run up these few days. Some are still waiting to see if a better offer or price comes up.
How about me?
On one hand I'm glad my previous thesis (suspicions) about M1 being a prime candidate for M&A has proven to be right.
On the other I am still excited to see how the various initiatives and ventures implemented by M1 will work out.
Anyway back to the purchase offer by Konnectivity Pte Ltd, at $2.06 I feel the downside is fairly limited. Also I believe the upside offers further magnitude with Axiata considering joining in the fray too.
Hence for now I will continue to hold and monitor for further news which I reckon we should be hearing within these couple of weeks.
Thursday, 3 May 2018
March and April 2018 Updates
Dividends received for these two months:
1) RHT Health Trust $122.00
2) M1: $744.00
Portfolio value as of now:
$113,149.50
Extraordinary expenditure:
Fine for waiting at unloading bay: $110.00
Thoughts:
Will continue to work hard to build up my income portfolio though warchest has definitely been affected due to lesser income available as I started my own company last year.
What I'm drawing now is about half of what I was getting when I was a partner at the previous firm. I intend to keep it that way until business has stabilised.
Jiayou, gambatte JASS. You can do it!
Wednesday, 11 April 2018
Takeaways from M1 AGM 2018
M1 AGM 2018
Date: 11/04/2018
Duration: 2.30 - 3.55 pm
Turnout: Full house (I nearly couldn't get a seat until an M1 staff led me to an empty seat at the 2nd row.
Questions from the floor
Q: Explanation for the higher EBITDA and lower net profit.
A: This is due to higher amortisation* for new investments such as narrow band internet of things (NBIOT).
* rightfully EBITDA should be before amortisation.
NBIOT is largely for B2B. Earnings from this segment takes time as things like smart meterings, smart lamp posts, smart flood monitoring, etc takes time to develop.
Q: How will M1 defend against the new Telco entrant?
A: M1 will continue to invest in their Telco business. However they do not intend to engage in price war.
Q: Can M1 diversify from its traditional source of income to reduce its vulnerability?
A: M1 is actually quite glad that they are not in the pay-tv segment due to players such as Netflix.
M1's fixed services grew 24.5% and M1 is pushing on that area.
M1 is not sitting just on mobile. They are looking for opportunities such as acquisitions.
Q: Can M1 lower their CAPEX than that of TPG's?
A: TPG stated their CAPEX as $250 M. However M1 estimated the figure should be $500 M instead.
Moving forward M1's CAPEX will be around $100 - 120 M.
Q: How does M1 intends to deal with the ~$200 M spectrum fee paid?
A: Amortise it over 15 years.
Q: How will M1 handle the high cost of interest payments to avoid affecting the dividends payout?
A: M1 has short term facilities to use.
Rights issue is not likely unless it's a last resort.
M1 used bank loans as those have the cheapest cost among all options including bonds.
Q (interesting as it tells us the operational readiness of TPG): Status of TPG now?
A: TPG has 200 base stations now. Some of them are interconnected.
M1 has 2,500.
Q: M1 already has a $450 M bank loan. How does M1 intends to fund the new spectrum?
A: M1's gearing is still low compared to the Telco industry. They can still borrow from their short and medium term facilities.
Q: How does M1's board feels about M1's future in the next 5 years which are challenging?
A: Acknowledged that next few years are indeed challenging.
They will be controlling costs.
M1 also has avenues to increase revenues but these take times.
The suffering revenue from mobile segment can hopefully be covered by these new sources of revenues, which might even be more than that of the mobile segment.
Q: How does M1 retains customers instead of them porting around?
A: Through sunrisers for high spenders, sunperks points and multisaver discounts.
M1 is also the Telco of choice for MPA due to their superior 4.5G network.
Q (this is my favourite question among all): What is the growth plan of M1? Does M1 intends to venture overseas? There's only one new entrant and yet M1's share price has fallen by half from its peak.
A: M1 is apprehensive about the start up costs of venturing overseas.
Telco industry is high cost, not like setting up a bank overseas.
Telco industry is also a highly regulated one to enter.
M1 has to be realistic about their financial capability. To raise funds for overseas venture, M1 has to ask money from the shareholders and the 3 major shareholders have to agree first.
However there are many ways to expand abroad. One way is through partnerships. E.g. to bring M1's IoT capability to the overseas market.
Q: CAPEX is high last year. How does M1 intends to arrest that?
A: M1 is investing for the future. And that is reflected in the high CAPEX and acquisitions.
Moving forward, estimated CAPEX will be lowered to $100 - 120 M per year.
Comment from one of the shareholders: M1's website is old-fashion and doesn't appeal to the younger generation.
Resolutions: All passed.
The above are what I have garnered. I have probably missed out some questions as I was focusing on the replies from the board. I have also left out some which I feel is not that important.
Summary and my thoughts
M1 is reluctant to expand overseas to be a full fledge Telco like what TPG has done in Singapore. This is due to their financial capability.
This in my opinion, is a double-edge sword.
By doing so they are limiting their growth as Singapore is only this big. However this also limits their risk to external environments of which a single mistake might wipe out all the cash generated so painstakingly especially since their financial capability is not big.
For M1, their focus now is controlling costs and continue to build on to their mobile base. Growth comes from their new initiatives such as the IoTs which I personally find promising in terms of being a new revenue driver for M1.
Personally I will continue to stay vested in M1 since the dividend yield is still attractive while I awaits the contributions from the new sources.
Tuesday, 16 January 2018
My Money-Saving Tips Towards Becoming a (Millionaire)
Okay. These tips might not help much towards becoming a millionaire.
However living in Singapore is not easy when things are not exactly cheap.
Hence in order to live more comfortably we have to build up our savings for the proverbial rainy days (not the kind that we experienced these few days) and at the same time achieve income increment that at least beat the inflation rate.
There are essentially two ways to go about achieving the former.
One: Increase our income.
Two: Decrease our spending.
Easy isn't it?
Since increasing our income isn't always within our control especially when it comes to salary, the other way is to look out for money-saving opportunities in our daily lives.
As a matter of fact, I did not consciously set out to do these acts. Somehow they have became part and parcel of my life after so many years, so much so that it is almost natural.
So here is goes.. Some of my money-saving tips for sharing..
1) Not ordering canned drinks at coffee shops
Canned drinks are by far the most price-inflated drink in a typical coffee shop. For the same canned drink that costs $1.50 at the coffee shop, I can get it at the neighbouring super market at half the price or less. Luckily I'm not a particular fan of canned drinks too.
2) Return appetisers and wet tissues in restaurants
Usually restaurants place appetisers like peanuts and pickles to your table before you even begin ordering your meal. However since I don't really fancy appetisers like these, I usually ask the staff to bring it back.
Same for the wet tissue. I don't really mind using my handkerchief or own tissue to wipe my mouth after meal.
3) Always check the bill
This is important. Always check your bill before and after payment. I have on more than one occasions been billed wrongly at eateries and super markets.
Simply by checking, I have saved quite a sizeable amount over the years.
This also applies to all your purchases, not only for meals and groceries.
4) Buy Online
I'm not saying everything must be bought online. Personally for items such as shoes, I still prefer to buy in brick and mortar shops.
However certain things like hand phone covers, casual attires and household items do indeed cost much lesser than in physical shops.
One of my recent online purchase:


Cost me a grand total of S$47.90 and 1 hour for assembly. Worth it isn't it?
5) Compare and Compare
This has been my habit for the longest time whether in my private life or in my work.
Shops like Watsons and Guardian are often located near each other in the mall. It helps to compare the price of same product between similar shops before buying. Sometimes the price difference can be significant.
6) Bulk pack isn't always cheaper
Again, this require some work on your part. Whip out your hand phone and calculate the unit price of the bulk pack item that you are eyeing.
There are times where we found the single pack is in fact cheaper than the unit price of the bulk pack of the same item.
7) Discount cards
Member cards like the Kopitiam card need no introduction. 10% discount off meals by using the card is a no brainer.
I don't usually pay to sign up for member card. But sometimes I do that if the advantages outweigh the price. For example I am a Jumbo member as I figure the savings achieved easily exceed the member fee.
8) Use credit card as far as possible
My style is to use my credit card as far as possible especially for big ticket items.
Nowadays cards like OCBC 365 card and UOB One card are tied to the respective savings account. By using the card, I can get cash rebate on my card and increased interest on my savings. Win-win.
Importantly: Pay off all the bills before due date.
9) Movie tickets
Yes I do watch movies too though I may sound miserly from above.
The trick here is to buy the tickets on the spot instead of online. Simple enough but I have friends who like to buy online thus incurring unnecessary surcharges.
However I heard from a friend that the surcharge is a fixed amount no matter how many tickets are bought. If that's true then bulk purchase of tickets might be worth it after all.
Having said that, I have an even better deal when it comes to movie tickets. As a M1 customer, I get to watch movies for free on Sundays! M1 customers enjoy one-for-one tickets on Sundays at Shaw cinemas. It used to be Cathay cinemas though.
Caveat is that I need to wake up early to buy the tickets as there is a limited number to this deal.
Nevertheless to me, it pays to wake up early and at the same time I get to spend more quality time with my loved ones.
10) Free parking
I always look out for free parking when I drive. It costs a lot to drive in Singapore so every little saving helps.
Certain malls offer free 2 hour lunch time parking.
Some areas offer free parking after 5 pm.
On Sundays there are plenty of free parking in estates around our sunny island. Even those close to malls. Very often I see cars queuing up to enter the malls' car park. But just a stone throw away there is free parking available at a HDB block and I don't even have to wait to enter.
Some times the free car park is 10 min walk away. But that is not an issue for me and my family. The walk back to the car park can be a nice time for a heart to heart talk.
Wednesday, 30 August 2017
August Updates
August has been a good month for me in terms of investments.
Dividends Collected
S$1,486.57
This comes from M1, SingTel, OCBC, CapitaLand Commercial Trust and Suntec Reit.
Stocks Purchased
Mapletree Logistics Trust @ S$1.185
This purchase forms part of my long term portfolio. Reasons for entering have been shared here.
Comfort Delgro @ S$2.18
Bought a second tranche when the price took a battering recently. This lowered my average price and subsequently I sold my holdings to take in some profits.
However I will enter CDG again once the opportunity arises as it is still a solid stock that I fancy and my belief in its fundamentals remains unchanged.
Wilmar @ S$3.11
I have been monitoring Wilmar for some time and when the price dropped recently to what I felt is a value with sufficient safety margin, I decided to make my maiden purchase into this commodities giant.
This will be a short term trade for me as it does not fits into my long term plan.
Stock Sold
Comfort Delgro @ S$2.33
Sold CDG for a small profit during the mini run up on news of possible collaboration with Uber. Decided to lock in the profits first for deployment elsewhere.

Last but not least, I received a bonus S$100 in the form of NS50 vouchers. Cheers!
Dividends
S$1,486.57
This comes from M1, SingTel, OCBC, CapitaLand Commercial Trust and Suntec Reit.
Stocks Purchased
Mapletree Logistics Trust @ S$1.185
This purchase forms part of my long term portfolio. Reasons for entering have been shared here.
Comfort Delgro @ S$2.18
Bought a second tranche when the price took a battering recently. This lowered my average price and subsequently I sold my holdings to take in some profits.
However I will enter CDG again once the opportunity arises as it is still a solid stock that I fancy and my belief in its fundamentals remains unchanged.
Wilmar @ S$3.11
I have been monitoring Wilmar for some time and when the price dropped recently to what I felt is a value with sufficient safety margin, I decided to make my maiden purchase into this commodities giant.
This will be a short term trade for me as it does not fits into my long term plan.
Stock Sold
Comfort Delgro @ S$2.33
Sold CDG for a small profit during the mini run up on news of possible collaboration with Uber. Decided to lock in the profits first for deployment elsewhere.

Last but not least, I received a bonus S$100 in the form of NS50 vouchers. Cheers!
Tuesday, 29 August 2017
Surprise Call from M1
I have always been satisfied with M1's customer service in my close to 20 years with them.
From the way they handled my queries over the phone to their staff at the front line, perhaps I have been lucky. So far I'm pretty impressed with their flexibility and initiatives.
Today I received a call from one of their customer service officers who offered me a loyalty voucher with quite a substantial amount to re-contract with them.
On top of that he also told me to delay my purchase (if any) to next month as phone prices will change after end of this month and Comex is coming so I might get a better deal!
I am pleasantly surprised as I was actually looking around for the past two weeks for a replacement for my 3 year old phone which apparently is nearing the end of its life 😞
Looking beyond the surface, this actually tells me that instead of being reactive to market changes, M1 is in fact proactively trying to retain customers.
Kudos to them 👏
Apart from that they are also coming up with promotions to get more customers on board. One example is the 300 mbps broadband plan @ $23 per month for the first year for customers who do not need a 'free' router.
I almost wanted to tell the CSO not to offer so many incentives especially handset subsidies to customers 😀
The above together with the initiatives I highlighted in my previous posts, further reinforce my belief that the sun will be shining brightly for M1 soon!
Friday, 18 August 2017
Wifey's S$20,000 Portfolio
Wifey recently got interested in investment for passive income too.
So one fine day she asked me to build up a dividend-paying portfolio for her with S$20,000 as the base capital.
The first thing I did was to look through my watch list for suitable stocks with dividend yield of at least 4%.
After identifying the stocks I waited for the opportune moment with comfortable price point to buy in for the long term.
After several weeks the first stock I bought is M1 at $1.86 pre-XD.
Weeks later, another opportunity arose. I bought Mapletree Logistics Trust at $1.185 when the price dipped.
Finally when the price fell yesterday, I bought Comfort Delgro at $2.18.
So as it stands wifey's portfolio now consists of the following:
M1 @ 4,000 shares (+ another 2,000 shares bought previously)
MLT @ 5,000 shares
CDG @ 3,000 shares
There are several more stocks in my watch list which will be added if the opportunity arises.
Friday, 28 July 2017
Recent Actions - June & July 17
Just to update my transactions for June and July 2017 as follows.
OCBC
Received some dividend last month for the scrips that I'm still holding on.
Always looking for a chance to enter OCBC again. But at current price points I would stay on the side line.
NetLink Trust
Will be keeping my 4,000 shares from the IPO for the long haul if the >5% annual dividend can be maintained. This is a more than decent yield considering our 'risk-free' interest from CPF SA is 4%.
Furthermore I see potential capital gain for this counter as well. Am secretly hoping this can eventually be a free holding for me.. Shhh 😀
M1
Taking advantage of the recent drop in price and added 2,000 shares to my holdings. Bought pre-XD at $1.86. Current total holdings @ 12,000 shares.
From the release of their 2Q results on 18th July to now, the share price has dropped from $2.10 to $1.785.
To me this is simply irrational. Seems artificial to me even. Looking at the broader scheme of things, is M1's performance so lousy that it warrants a 15% drop in a span of 8 trading days?
Not to me. I can understand if M1 becomes loss-making. But considering it's a profitable company, this simply baffles me. 😖
Perhaps.. Just perhaps.. is someone pressing the price down for a potential take over?
Just a wild guess. In the mean time I will consider adding more if opportunity arises.
mm2 Asia
Bought 5,000 shares when the price dipped to $0.51 on news of the stalemate at buying over GV.
I'm more of a dividend investor than growth or value, however I see an opportunity for a short term capital gain at this price. Time will tell whether I'm right or wrong.
Plus it wouldn't hurt to try balloting for free concert tickets isn't it? 😁
Wednesday, 19 July 2017
Why I Feel M1 is a Potential Winner
With the release of the results yesterday, the selldown in M1 is expected today.
The magnitude of drop also doesn't surprised me. Afterall it has happened not too long ago during the announcement of the 4th entrant.
This is a classic example of market (people) sentiment.
People seldom look beyond the surface. Yes M1's earnings dropped. But they are still profitable. It is a company still making money and churning out decent dividends.
Furthermore as announced in their AGM, they are branching out into other stuffs apart from their traditional income. Stuffs such as smart metering and IoT. It takes time to realise the fruits from these plantings.
But the most important thing is this:
M1 is a prime candidate for M&A.

Considering the high barrier of entry into the telco sector, if I were a conglomerate looking to enter, I would seriously consider buying over the current players with existing infrastructure and customer base instead of starting from the ground.
Among the 3 incumbents, M1 looks attractive.

And we already have a hint to that happening recently. The interest is there. Buyers are willing to buy just that the seller is not willing. For now.
However I believe this is not the end of story. On the contrary this is just the beginning.
We will soon see more news on the takeover of M1 from this point onwards.
Usually deals like this takes a long time before coming to fruition. Just look at GLP.
* Extremely bias view with vested interest.
Tuesday, 30 May 2017
Recent Actions - April & May 17
Just a quick update on my stock related activities for the past two months.
S$1,282 contra loss on Rotary Engineering.
S$590 M1 dividends received.
S$121 Comfort Delgro dividends received.
S$400 Capitaland dividends received.
S$97 Suntec Reit dividends received.
On the watch list, some of the counters have been inching towards or have reached my buying target price.
I am keeping a close eye on:
ISOTeam - to add more on further dips
Raffles Medical, ThaiBev and Wilmar - to initiate position
Will enter when the time arrives.
I have not been that successful in trading recently. However at least I know what went wrong. Will definitely keep these lessons in mind.
Last but not least, I hope to be more active in the market in the coming months. But I won't buy just for the sake of buying. After all a bird in hand is worth two in the bushes.
S$1,282 contra loss on Rotary Engineering.
S$590 M1 dividends received.
S$121 Comfort Delgro dividends received.
S$400 Capitaland dividends received.
S$97 Suntec Reit dividends received.
I am keeping a close eye on:
ISOTeam - to add more on further dips
Raffles Medical, ThaiBev and Wilmar - to initiate position
Will enter when the time arrives.
Last but not least, I hope to be more active in the market in the coming months. But I won't buy just for the sake of buying. After all a bird in hand is worth two in the bushes.
Thursday, 9 February 2017
Random Thought on M1
Many people are talking about how bad the outlook is for M1.
Yes, top and bottom lines are declining. But I feel it is not gloom and doom for M1. Afterall they are still making money isn't it? Not as if they are loss-making.
I believe their turnaround will be when their new initiatives such as IoT and smart meters start to kick in and generate revenues for them.
My feeling is that the M1 now is like the SingTel years ago when they started to diversify into new income streams which they are now reaping the benefits.
Am I the only one feeling this way?
However there is a key factor to M1's future outlook as follows:
Potential upside: Ms Karen Kooi
Potential downside: Ms Karen Kooi
Thursday, 26 January 2017
Little Milestone for the Blog
Just realised my blog has crossed the 1,000 readership mark in a little less than a month after my first post Inaugural Post.
Although it's not a big achievement to speak, I'm still happy that my posts are being read by people and hopefully be of help too.
There's no comment to my posts so far, but whoever you are, thank you for your time in reading.
Quick update on the market:
Dow Jones has finally broke the 20,000 mark. This should bodes well for the STI which has enjoyed a bull run so far into the new year.
Looks like Trump putting his words into actions is generating a positive feeling in the market. As the saying goes - people are fearful of the unknown. The feeling should be gone now judging from the breakthrough in DJIA.
On a personal note:
CapitaLand proved to be a good buy so far. However M1 suffered from panic selling yesterday due to the release of their latest results. I expect the share price of M1 to rebalance after this and rebound.
Hopefully the tangible benefits of their collaboration with Starhub will come sooner.
I have also added a few more counters into my watch list recently.
Moving forward will continue to look out for suitable buys to add to my long term portfolio and experiment with some short term tradings to slowly build up my warchest again.
Tuesday, 10 January 2017
STI Break Through 3,000 Finally
Today is a happy day for many. Finally STI broke through 3,000 points. The last time it happened is 14 months ago which seem like a long time amidst the turmoils last year.
Good news for me is that most of my counters including new ones like CapitaLand which I purchased at $2.98 are in the green zone.
Even those in the red like M1, are sustaining less damage because of the bull.
Bad news is I haven't got the chance to do some trading because of work. I am heavily involved in a project now which is scheduled for completion before CNY.
Will this bull continues to charge forward? Or will it slows down shortly and hibernate like a bear?
Honestly I'm in two thoughts. If it continues and hit my TP for some of my counters I will probably sell to realise the profits.
If the market retracts it will not affect me too much either as my investments are mostly on a longer term horizon. In fact I will take the chance to continue sourcing for good buys to add to my portfolio.
Either way I will make money. Opps, touch wood and cheers!
Subscribe to:
Posts (Atom)